Revolut is a full UK bank. Most earlier app banks took six years or more to profit.
After a 5-year application and 20 months of restricted trading, the Prudential Regulation Authority lifted Revolut's limits. It is now a full UK bank.
What happened
The PRA approves Revolut Bank UK to launch without restrictions, ending a mobilisation phase that ran nearly twice the standard length.
Revolut became a full UK bank on . That day the Prudential Regulation Authority (PRA), which oversees banks, lifted the limits on Revolut Bank UK. Revolut applied in 2021. It got a restricted licence in , with deposits capped at £50,000 while it finished building the bank. That start-up stage is meant to take around twelve months. For Revolut it took nearly two years.
Francesca Carlesi, Revolut’s UK chief executive, called the approval a defining moment for Revolut. Current accounts open to new customers within days, starting with a small group. Existing UK customers move to the bank in stages over several months. Eligible deposits are now protected by the Financial Services Compensation Scheme.
The licence lets Revolut offer products it could not sell as an e-money firm: personal loans, credit cards and, later, mortgages. It also sharpens a question the company has faced since its last funding round, which is where a business this size lists its shares. Revolut has applied for a US national bank charter and has repeatedly declined to commit to London.
The Pattern
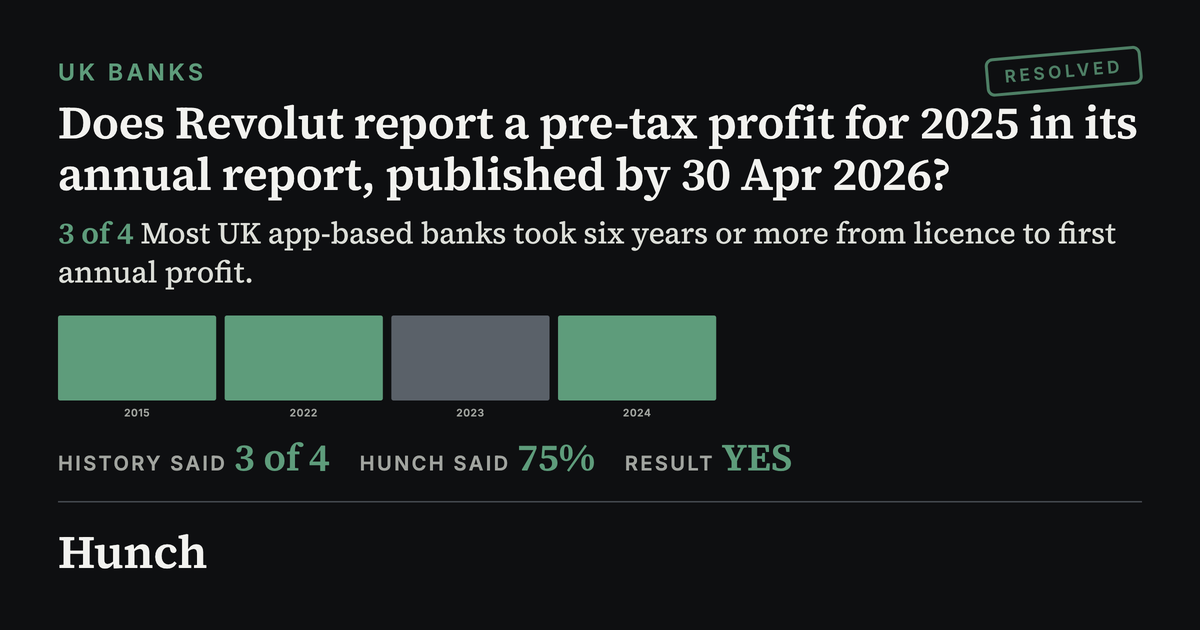
A UK banking licence is only the start. We looked at the app-based banks licensed in the UK before Revolut and counted the years from licence to their first yearly profit. Most took six years or more. Zopa did it in three.
Show the other 2 cases
The Read
History says profit comes slowly after a licence, but Revolut starts from a different place. It gets its full UK licence with more than 60 million customers worldwide, and the group already reports billions in revenue and a large pre-tax profit. The earlier banks spent their first licensed years looking for a way to make money. Revolut already has one and is adding a UK bank to it. Expect loans sooner than the history suggests, because the pressure to earn more from UK customers is immediate.
The long wait for the licence is itself a warning. A start-up stage that ran nearly twice the usual length shows a regulator that needed convincing. Full status also brings full supervision of capital and financial crime controls, at a scale no UK app bank has faced on day one. Monzo’s £21m FCA fine in 2025 showed what happens when growth outruns controls. Moving millions of accounts is also the kind of job that makes headlines when it goes wrong.
Revolut’s 2025 annual report, due by , will show whether the profit holds up. A live UK loan product would show how fast the new bank moves.
Disclaimer
Hunch works only from sources that are publicly available, and publishes on the basis of analysis of that material. We do not form an editorial opinion or take sides, we give a simpler and wider view of news that already exists. If information in a source we used was inaccurate, distorted, or later disputed but had already entered our analysis, Hunch accepts no liability for that. Predictions are not advice. Phase 1 markets use Hunch Points, not money.
Published by Hunch under the Editorial Code. Complaints and corrections: /contact/.